Waiting to Refinance? Here's What the Data Actually Says Right Now

Vantage Fall 2026 Newsletter
Mortgage & Economic Update: Why Rates Are Moving Again
If it feels like mortgage rates have been on a roller coaster lately, you’re not imagining it.
Mortgage rates improved earlier this summer before reversing course more recently as financial markets began digesting a combination of stubborn inflation, rising energy costs, geopolitical uncertainty, and changing expectations for Federal Reserve policy.
What’s Driving Mortgage Rates?
One of the biggest misconceptions about mortgage rates is that the Federal Reserve directly sets them. It doesn’t.
Mortgage rates are much more closely connected to the bond market, particularly longer-term U.S. Treasury yields and mortgage-backed securities. Those markets are constantly looking ahead and pricing expectations for inflation, economic growth, government borrowing, and future monetary policy.
Right now, inflation and energy prices are back in the spotlight.
Energy costs have risen sharply compared with a year ago, with gasoline prices contributing significantly to the latest increase in consumer inflation. Higher energy costs matter because they don’t just affect what we pay at the pump. They can increase transportation, manufacturing, food, and distribution costs throughout the economy.
That creates a problem for interest rates.
The Federal Reserve wants inflation moving sustainably toward its 2% target. However, recent inflation data has remained elevated, while the broader economy has continued to show resilience. The Fed responded in September by raising its benchmark rate for the first time in several years.
For mortgages, however, what matters most isn’t simply what the Fed did. It’s what the bond market believes happens next.
If inflation continues cooling and economic growth slows, that could create an environment for mortgage rates to improve. If inflation remains stubborn, energy prices continue climbing, or the economy stays stronger than anticipated, longer-term rates could remain elevated or volatile.
That’s why we continue to monitor the markets closely rather than trying to predict one specific direction.
Shopping Your Mortgage & AI
Your home and mortgage is one of the largest financial decision of your life – and most people compare the wrong numbers and trust the wrong sources. Here at Vantage, we have created a Smart Shoppers Guide that explains the numbers you need to look for, what traps to avoid and how to vet any lender in about 10 minutes. We also discuss the cons of relying solely on AI assisted shopping and clarify how to use AI effectively in helping you search.
You can read our guide HERE
A Reminder To Our Past Clients: Call Us Before Your Next Mortgage
This may be the most important part of this update.
Before you buy another home, refinance, purchase an investment property, or accept an offer from your current mortgage servicer, please call us.
As an independent mortgage broker, our responsibility is to work in our clients’ interests. We have access to multiple wholesale lenders and can compare options rather than having your loan automatically placed with one company.
We’ve recently reached out to several past clients who sold their homes and purchased new ones or refinanced directly through their existing loan servicer without contacting us.
Unfortunately, some discovered afterward that they had accepted higher rates, higher fees, or both, without realizing that better options may have been available.
A mortgage servicer contacting you about a refinance already has something very valuable: your business.
They don’t necessarily have to compete for it unless you create competition.
That’s one of the biggest reasons independent mortgage brokers exist.
One conversation with our local team allows us to shop and compare multiple lenders on your behalf. Even if the offer you already have turns out to be the best option, you’ll have the confidence of knowing it was actually compared.
There is never an obligation to use us. We simply want our past clients to give us the opportunity to make sure the market is competing for their business.
The Best Time To Buy A Home in 2026 Is Almost Here
Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.
Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.
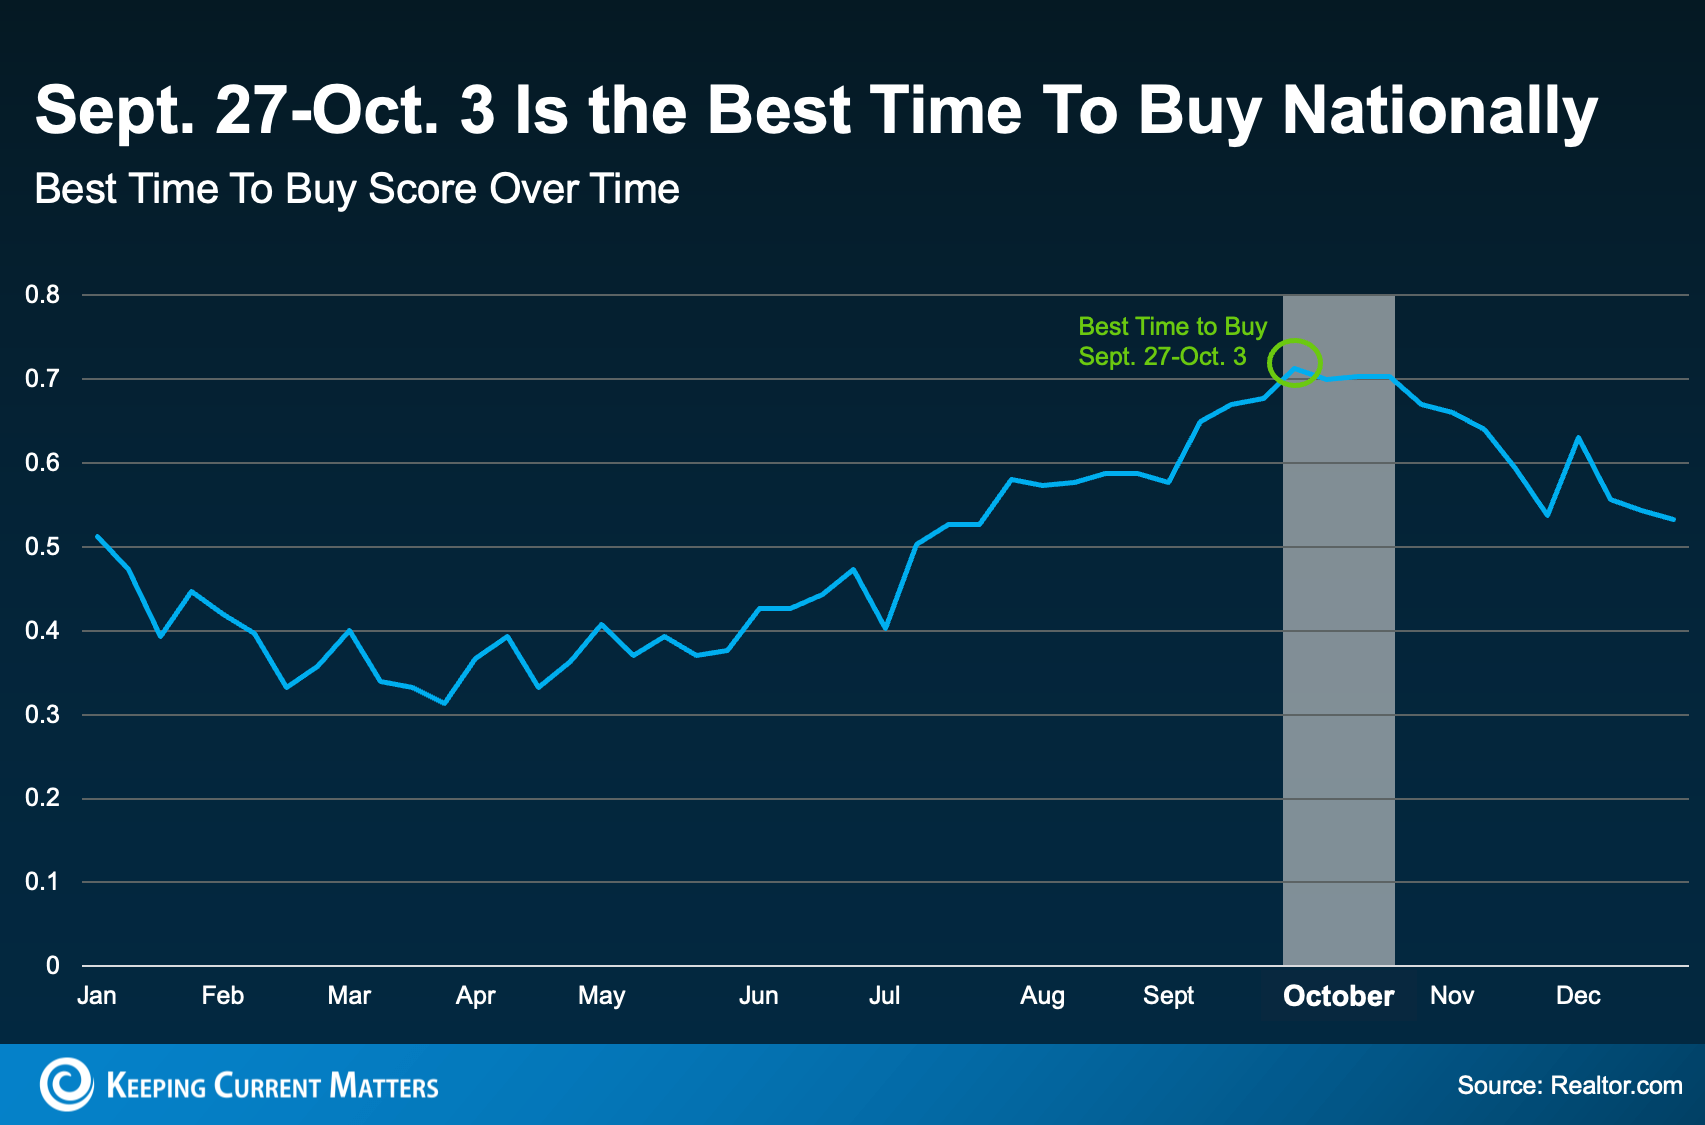
According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:
“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence.”
But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):
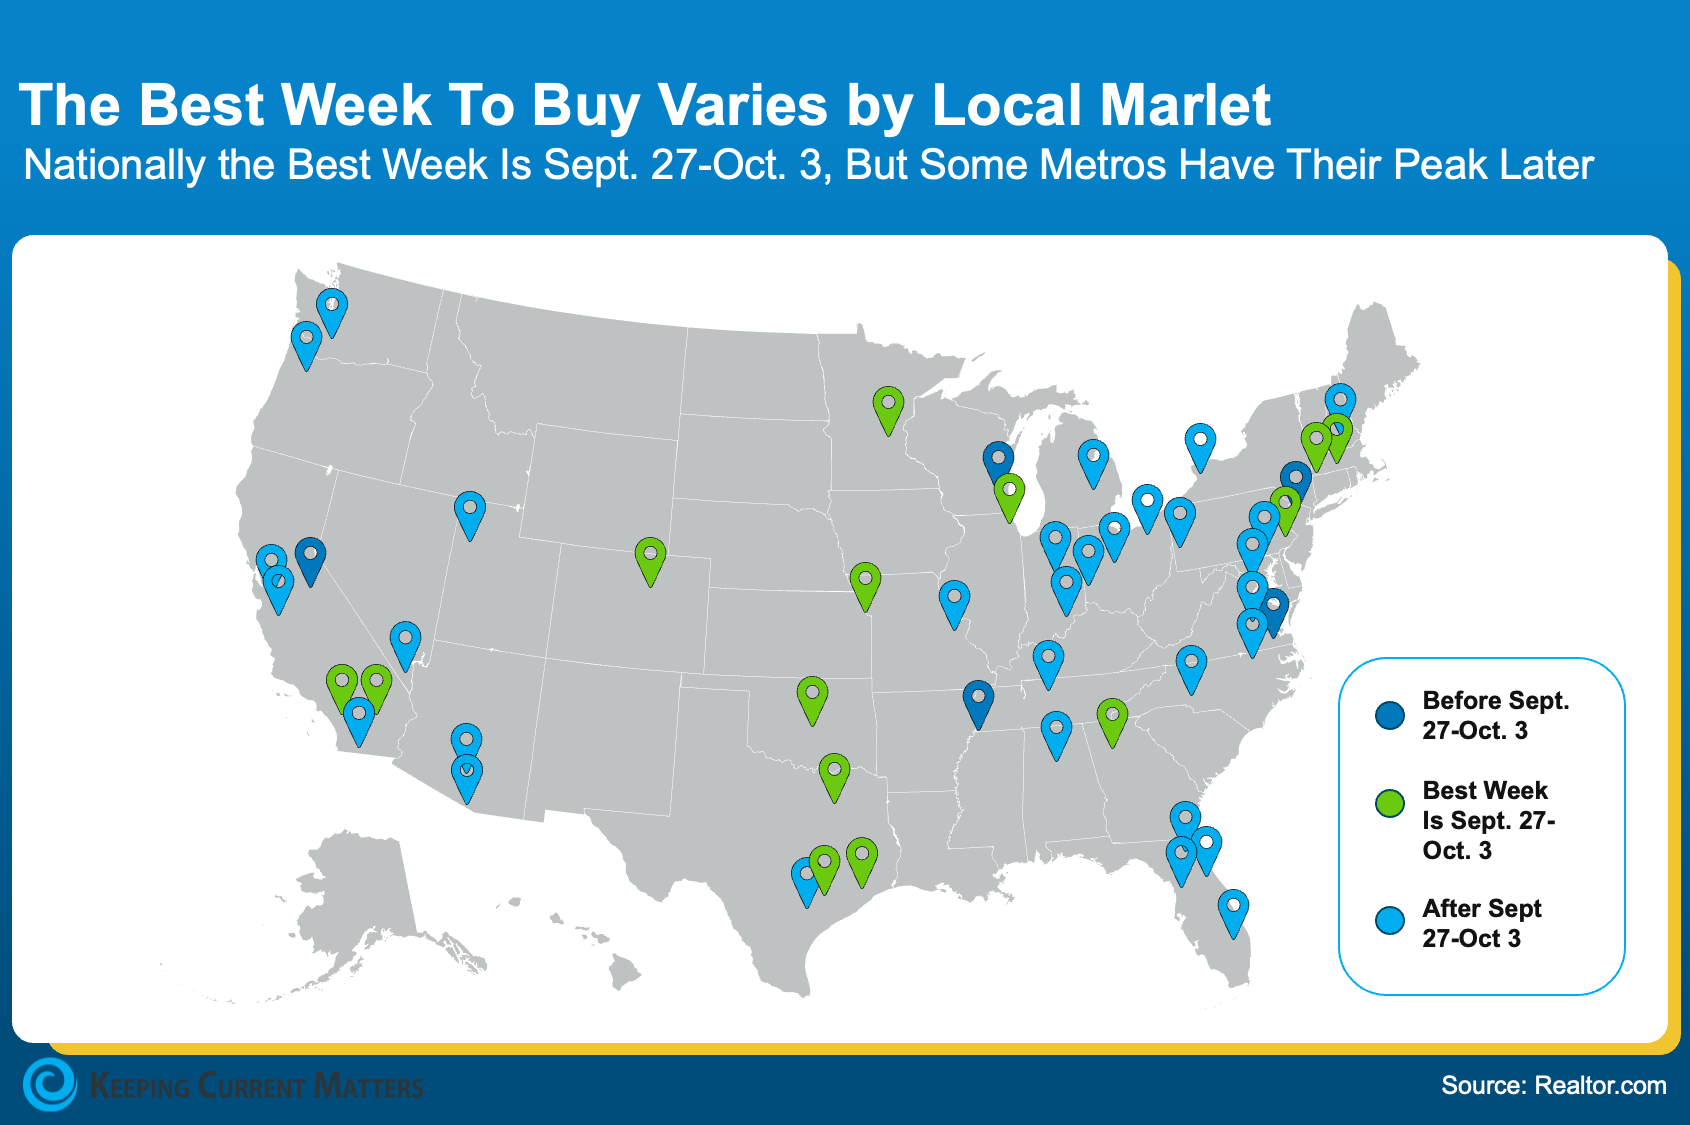
It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.
More Choices, Better Prices, and Less Competition
For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:
“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”
That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.
Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision.
More choices.
Better pricing.
Less competition.
That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.
The Window Doesn’t Close After This One Week
But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October.
In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains:
“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”
Bottom Line
If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.
The Market Changed. Your Reason For Moving Didn’t.
You may be telling yourself you’re going to wait to move – maybe you’re hoping mortgage rates will come down, prices will fall, or the market will feel a little easier.
And honestly? A lot of people feel that way right now. But here’s what some are starting to realize.
Waiting doesn’t usually fix the thing that made you want to move in the first place.
Your family still desperately needs more room.
Your empty nest still feels too…empty.
Your parents or grandparents still need you to live closer.
You just got married… or divorced.
Your vision of retirement has you living somewhere else.
Eventually, life can reach a point where waiting feels harder than moving.
That’s why some people are still deciding to buy right now, even in today’s market. Not because conditions are perfect. But because the life changes behind their move never really went away.
And maybe that’s exactly where you are too. If so, you’re certainly not alone.
The Real Reasons People Move
Data from the National Association of Realtors (NAR) shows 1 in 5 buyers in 2025 said they felt like they had to purchase a home at that time, no matter the market.
That’s an important reminder right now. Sure, the dollars and cents of your move have to make sense for you. But big life changes happen whether mortgage rates and home prices are high, low, or somewhere in between.
And those big life events happen more than you may think. NAR says roughly 22.5 million people experience major life changes in a typical two-year span (see graph)
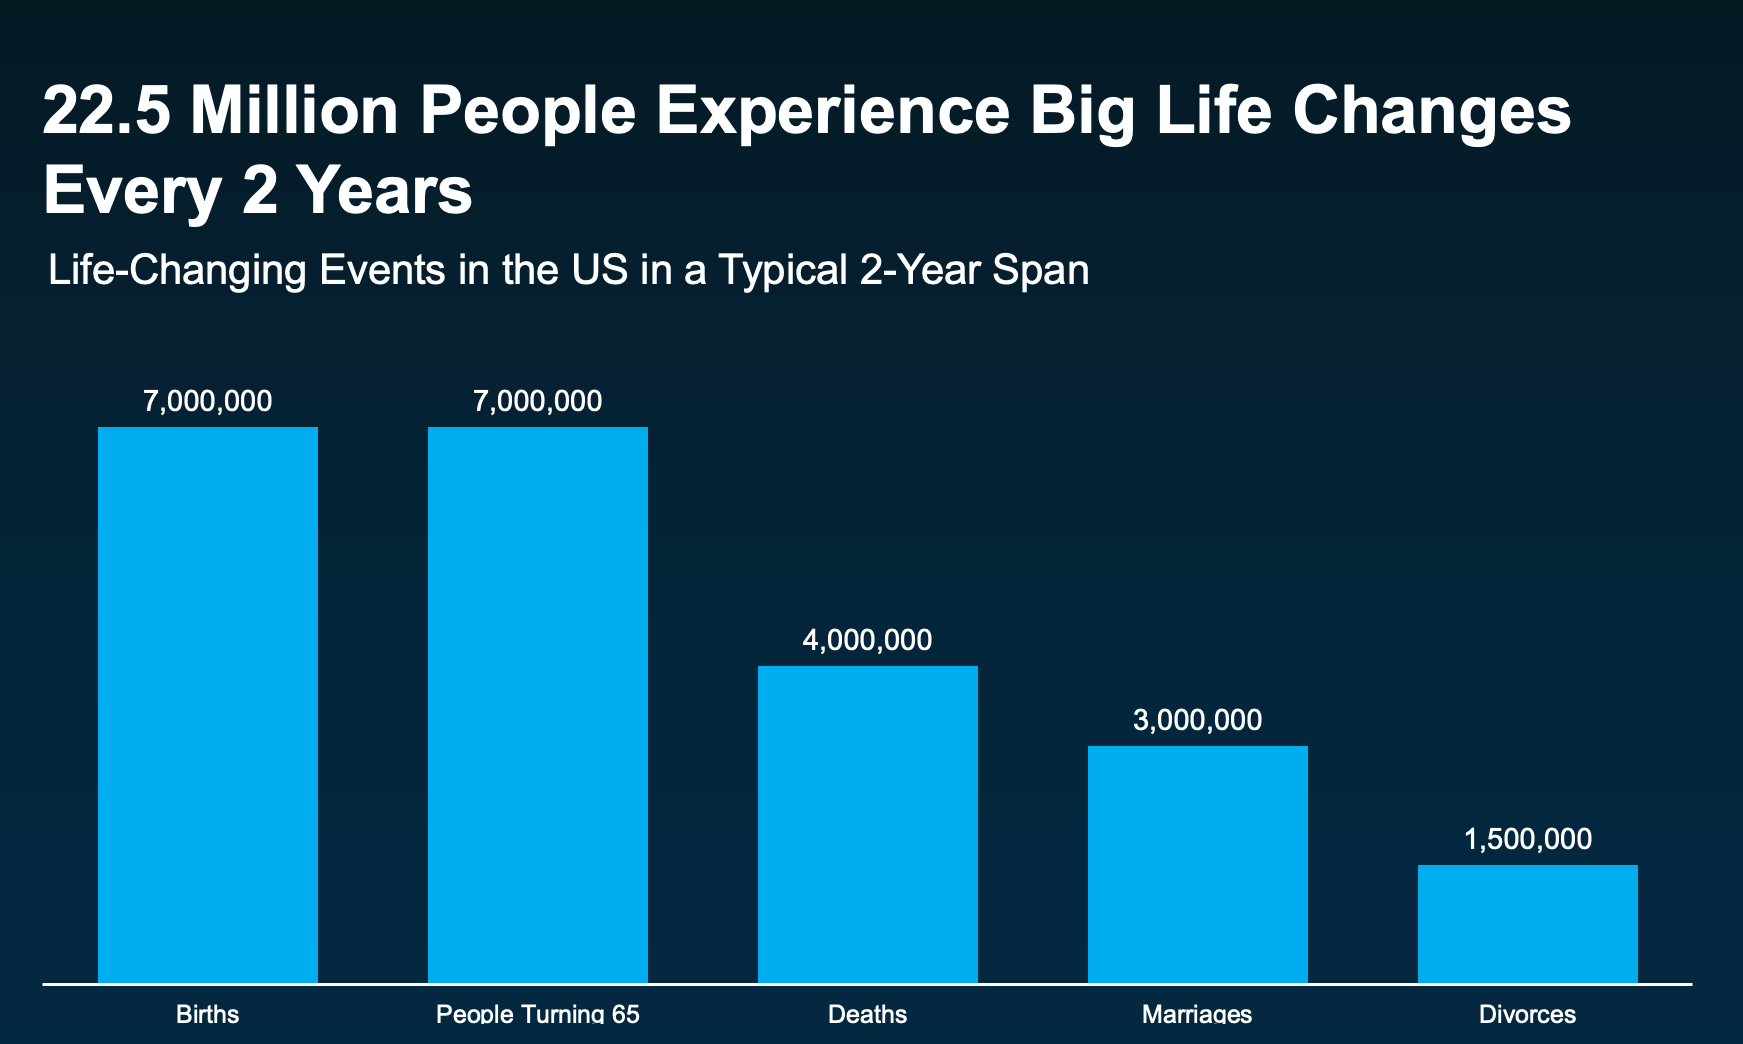
These are exactly the kinds of things that can change how much space you need, where you want to live, or what kind of lifestyle makes sense now. Chen Zhao, Head of Economics Research at Redfin, explains:
“Life doesn’t stand still—people get new jobs, grow their families, downsize after retirement, or simply want to live in a different neighborhood.”
And that’s what makes waiting so hard. Every month you spend hoping the market changes is another month living in a house that no longer works for your life. It’s stressful to feel stuck. And that feeling usually doesn’t disappear.
There May Be More Opportunity Than You Think
But while affordability is still a challenge, there may still be a way for you to make your move.
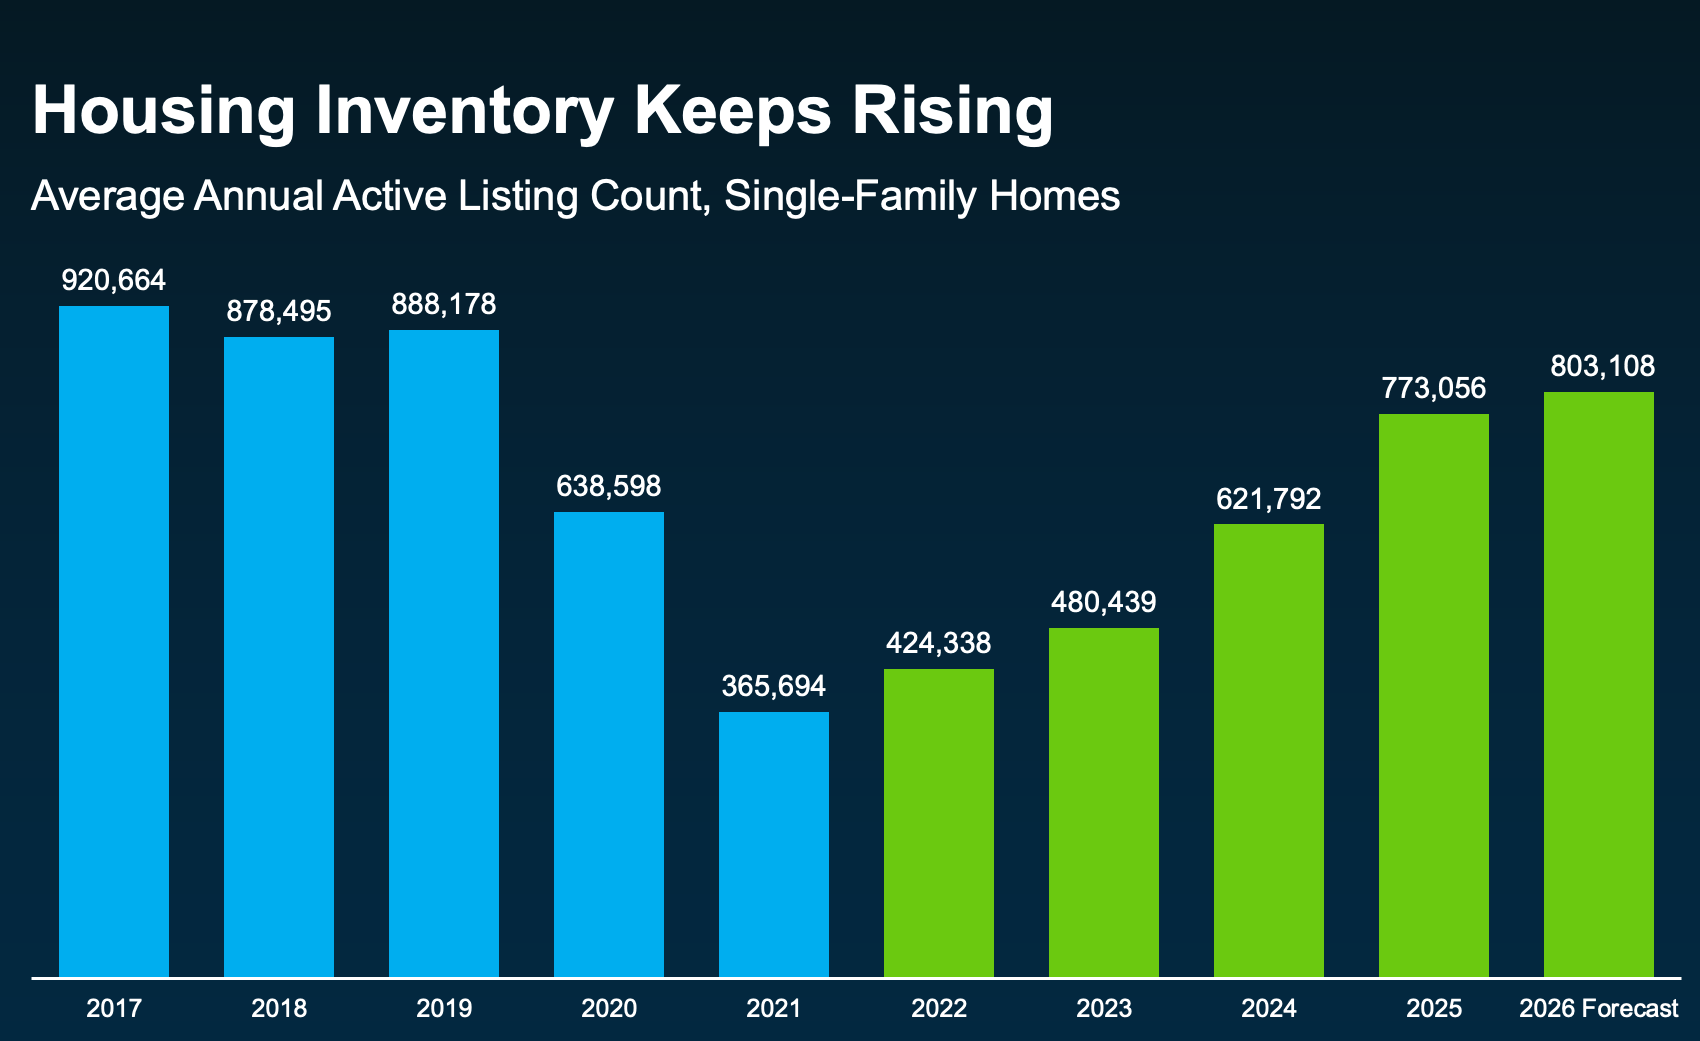
HousingWire Data shows the number of homes for sale has been growing for years (see graph below). That means more homes to choose from and, in some markets, more room to negotiate than buyers had just a few years ago.
That doesn’t mean moving is suddenly easy. But it does mean some buyers are finding ways to make a move work. So, if you’ve been putting your plans on hold, maybe the question isn’t just:
“What’s the market doing?” or “When will it get better?”
Maybe ask yourself this, too: “Can I still live where I’m at right now and make it work?”
If the answer to that second question is “no,” it may be worth having a conversation about what your options look like today – despite where rates or prices are. You could find your move is still possible after all. With more homes for sale, there’s a better chance to find one that fits your life (and your budget) right now.
Bottom Line
Life changes. Priorities shift. Families grow. Kids move out. Careers evolve. And eventually, the house you’re in may stop fitting the life you’re living.
If that’s been weighing on you lately, talk to us about what your options could realistically look like today, no matter where rates or prices are.
Life can’t always wait for perfect market conditions. Maybe you don’t have to either.
Worried About a Housing Crash? The Numbers Tell A Calmer Story.
A recent survey from Talker Research asked Americans to pick one word to describe how 2026 has felt so far. The winner? Stressful. And honestly, there’s been a lot going on.
So, it’s understandable if you’ve been putting off buying or selling a home until things settle down. But you may be waiting on something that’s already happened. While everything else has felt shaky, the housing market has become one of the steadiest things out there. Look at the data.
Home Prices Have Leveled Out
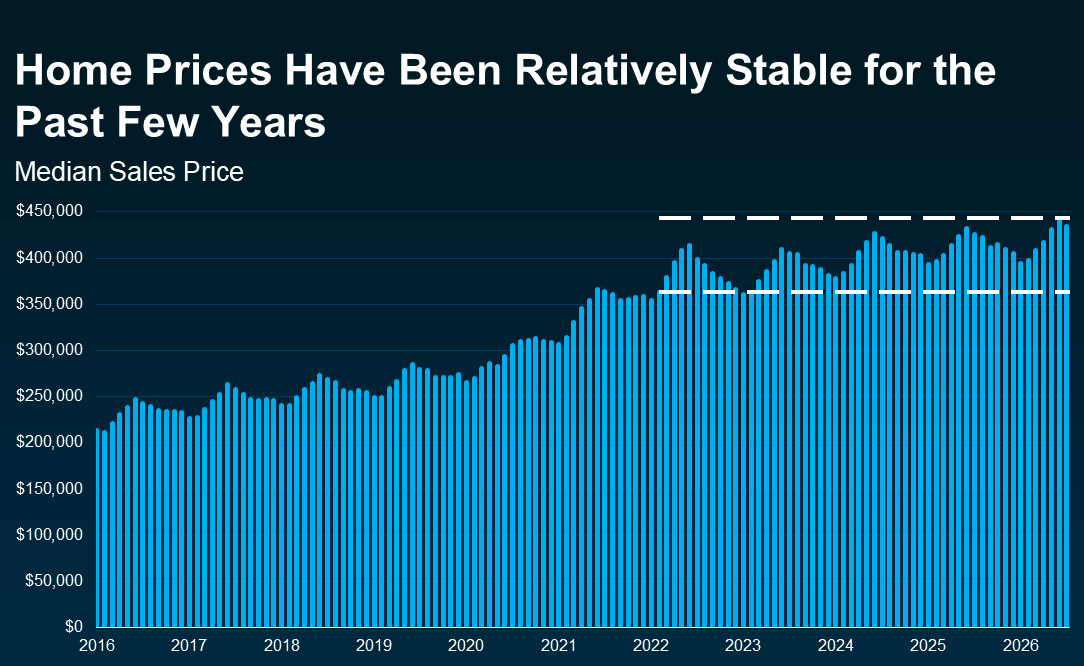
After years of fast increases, data from the National Association of Realtors (NAR) shows home prices have been remarkably steady for the past 4 years (see graph).
And experts say that’s what to expect going forward, too. As Selma Hepp, Chief Economist at Cotality, explains:
“In 2026, we expect home prices to remain broadly stable, with modest appreciation at a national level.”
No wild swings. Just slow, steady growth. That’s a healthy market. Of course, that pace can vary a bit depending on where you live. But nationally, steady growth like this makes it easier to plan your budget, whether you’re buying or selling.
The Supply of Homes for Sale Has Steadied
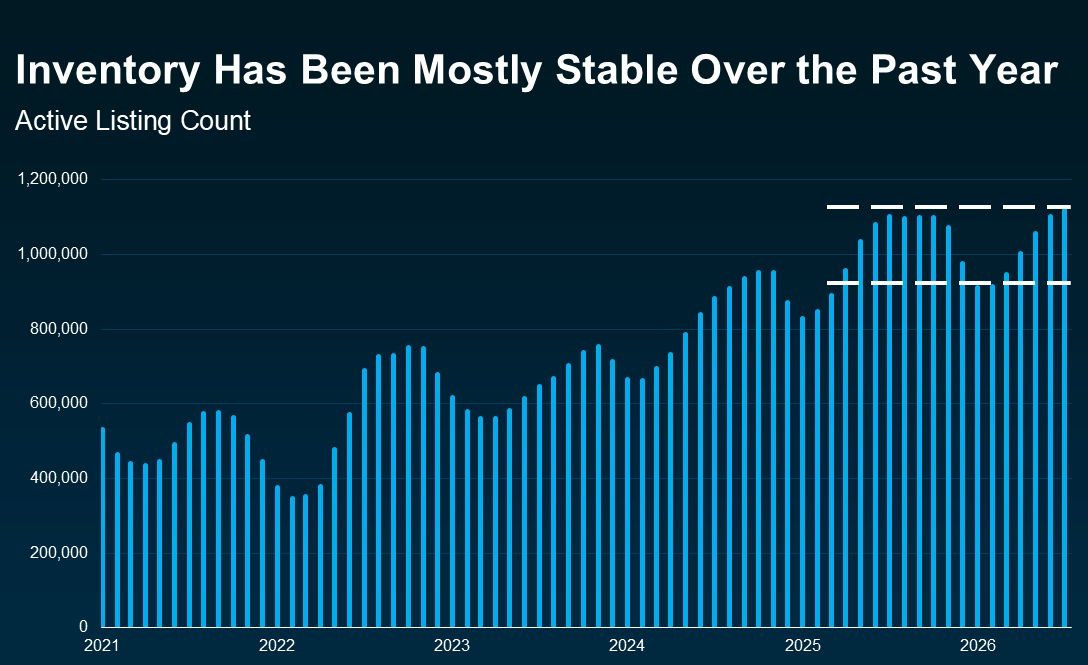
For years, the supply of homes for sale was a moving target. It dropped fast during the pandemic and has been climbing pretty reliably ever since. Now, that pace of growth has slowed down. According to Realtor.com, inventory today is very close to where it was this time last year (see graph).
That’s helpful no matter which side you’re on. When the number of homes for sale isn’t changing much, you know what you’re walking into – how many options you’ll have as a buyer, and how much competition you’ll face as a seller.
Mortgage Rates Found Their Range
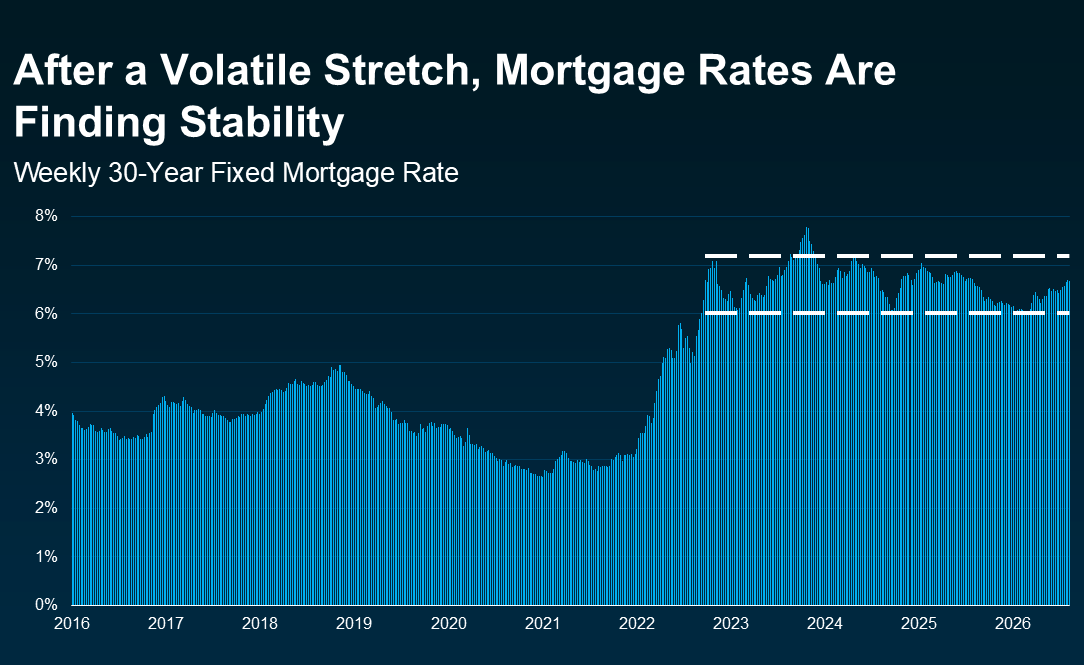
Yes, rates jumped dramatically back in 2022. But since then, Freddie Mac data shows they’ve stayed between 6% and 7% for the better part of the last 3 or so years (see graph).
Yes, there was one brief spike above that threshold, but overall, rates have stayed in that range for a while now. That predictability helps when you’re planning a move.
And now that this seems to be a longer-term trend, people have accepted it as the new normal. Buyers have gotten comfortable purchasing in that range, and sellers have gotten just as comfortable listing in it.
That comfort’s important because when both sides know what to expect, they keep making moves. In other words, the market isn’t frozen waiting for something to change. It’s moving calmly.
Bottom Line
The rest of the world may feel unpredictable right now, but the housing market doesn’t have to. Prices, inventory, and rates have all found solid ground.
If stability is what you’ve been waiting for, it’s already here. Connect with us today if you want to talk through what that means for your move.
OREGON HOUSING MARKET OVERVIEW
Median Sale Price:
$506,889
-0.61% year-over-year
# of Homes Sold:
3,896
-1.7% year-over-year
Median Days on Market:
39
-6 year-over-year
In August 2026, home prices in Oregon were down 0.61% compared to last year, selling for a median price of $506,889. On average, the number of homes sold was down 1.7% year over year and there were 3,896 homes sold in August this year, down 3,964 homes sold in August last year. The median days on the market was 39 days, down 6 year over year.
WASHINGTON HOUSING MARKET OVERVIEW
Median Sale Price:
$597,504
-2.8% year-over-year
# of Homes Sold:
7,102
-2.8% year-over-year
Median Days on Market:
32
+4 year-over-year
In August 2026, home prices in Washington were down 2.8% compared to last year, selling for a median price of $597,504. On average, the number of homes sold was down 2.8% year over year and there were 7,102 homes sold in August this year, down 7,308 homes sold in August last year. The median days on the market was 32 days, up 4 year over year.
IDAHO HOUSING MARKET OVERVIEW
Median Sale Price:
$512,859
+7.9% year-over-year
# of Homes Sold:
2,758
+10.1% year-over-year
Median Days on Market:
48
-5 year-over-year
In August 2026, home prices in Idaho were up 7.9% compared to last year, selling for a median price of $512,859. On average, the number of homes sold was up 10.1% year over year and there were 2,758 homes sold in August this year, up 2,506 homes sold in August last year. The median days on the market was 48 days, down 5 year over year.
We will always follow transparency and best practices at VMB:
- We embrace lender competition and shop our network of wholesale lending partners to ensure you receive accurate data and benefits without surprises later.
- We produce the rate sheet and all options for a detailed recapture analysis and understanding of the options now or in the future.
- We provide all costs or credits up front. We advise locking at application, as that makes the refinance to see terms that will not vary. We also provide the option to finance costs or not, with pros and cons.
- We embrace analytical accuracy on 3rd party closing costs and prepaids.
- We are confident in our ability to offer the most competitive options, but in the rare case we do not, we will tell you and confirm the best course of action.
Again, don’t hesitate to contact your VMB Broker for a quick update or to keep track of our custom loan comparison, benefits worksheet, and rate sheets.
THANK YOU FOR SUPPORTING A LOCAL SMALL BUISNESS!
Finally, we want to say thank you.
Our business has been built over many years through relationships, repeat clients, local real estate professionals, and referrals from people who trust us enough to introduce us to their friends and family.
That support matters more today than ever.
The mortgage industry has become increasingly dominated by enormous national lenders, servicing companies, call centers, online lead generators, and companies spending millions of dollars to acquire customers.
We’re different.
We’re a local small business. We live and work in the communities we serve, and our reputation depends on what happens after the transaction just as much as what happens during it.
When you refer someone to us, you’re not just sending us another transaction. You’re supporting a local business and allowing us to continue competing on behalf of consumers.
We don’t take that trust lightly.
So whether you’re thinking about buying, refinancing, investing, or simply wondering whether something you’re being offered makes sense, call us before making a decision.
And if you know someone who could benefit from having an experienced local mortgage team in their corner, we’d be grateful for the introduction.
Thank you for your continued trust, referrals, and support.
The Vantage Mortgage Brokers Team

Related Posts